
Roof insurance claims in Northern Virginia,
documented so nothing gets missed.
Storm damage is one of the few roof problems a homeowner's policy may help pay for. Our part is the evidence: dated photos of every slope, an itemized scope, and a roofer standing next to your adjuster. The claim itself stays between you and your insurer.
- Serving Virginia · DC · Maryland
- Licensed & insured
- Dated photos of every slope
- We meet your adjuster on the roof
- Your deductible is never "waived"
Sudden damage, yes. Old age, no.
Most homeowner's policies pay for damage that was sudden and accidental. They don't pay to replace a roof that wore out. Which column your roof lands in is the whole question, and it's the first thing we tell you on the inspection, before you file anything.
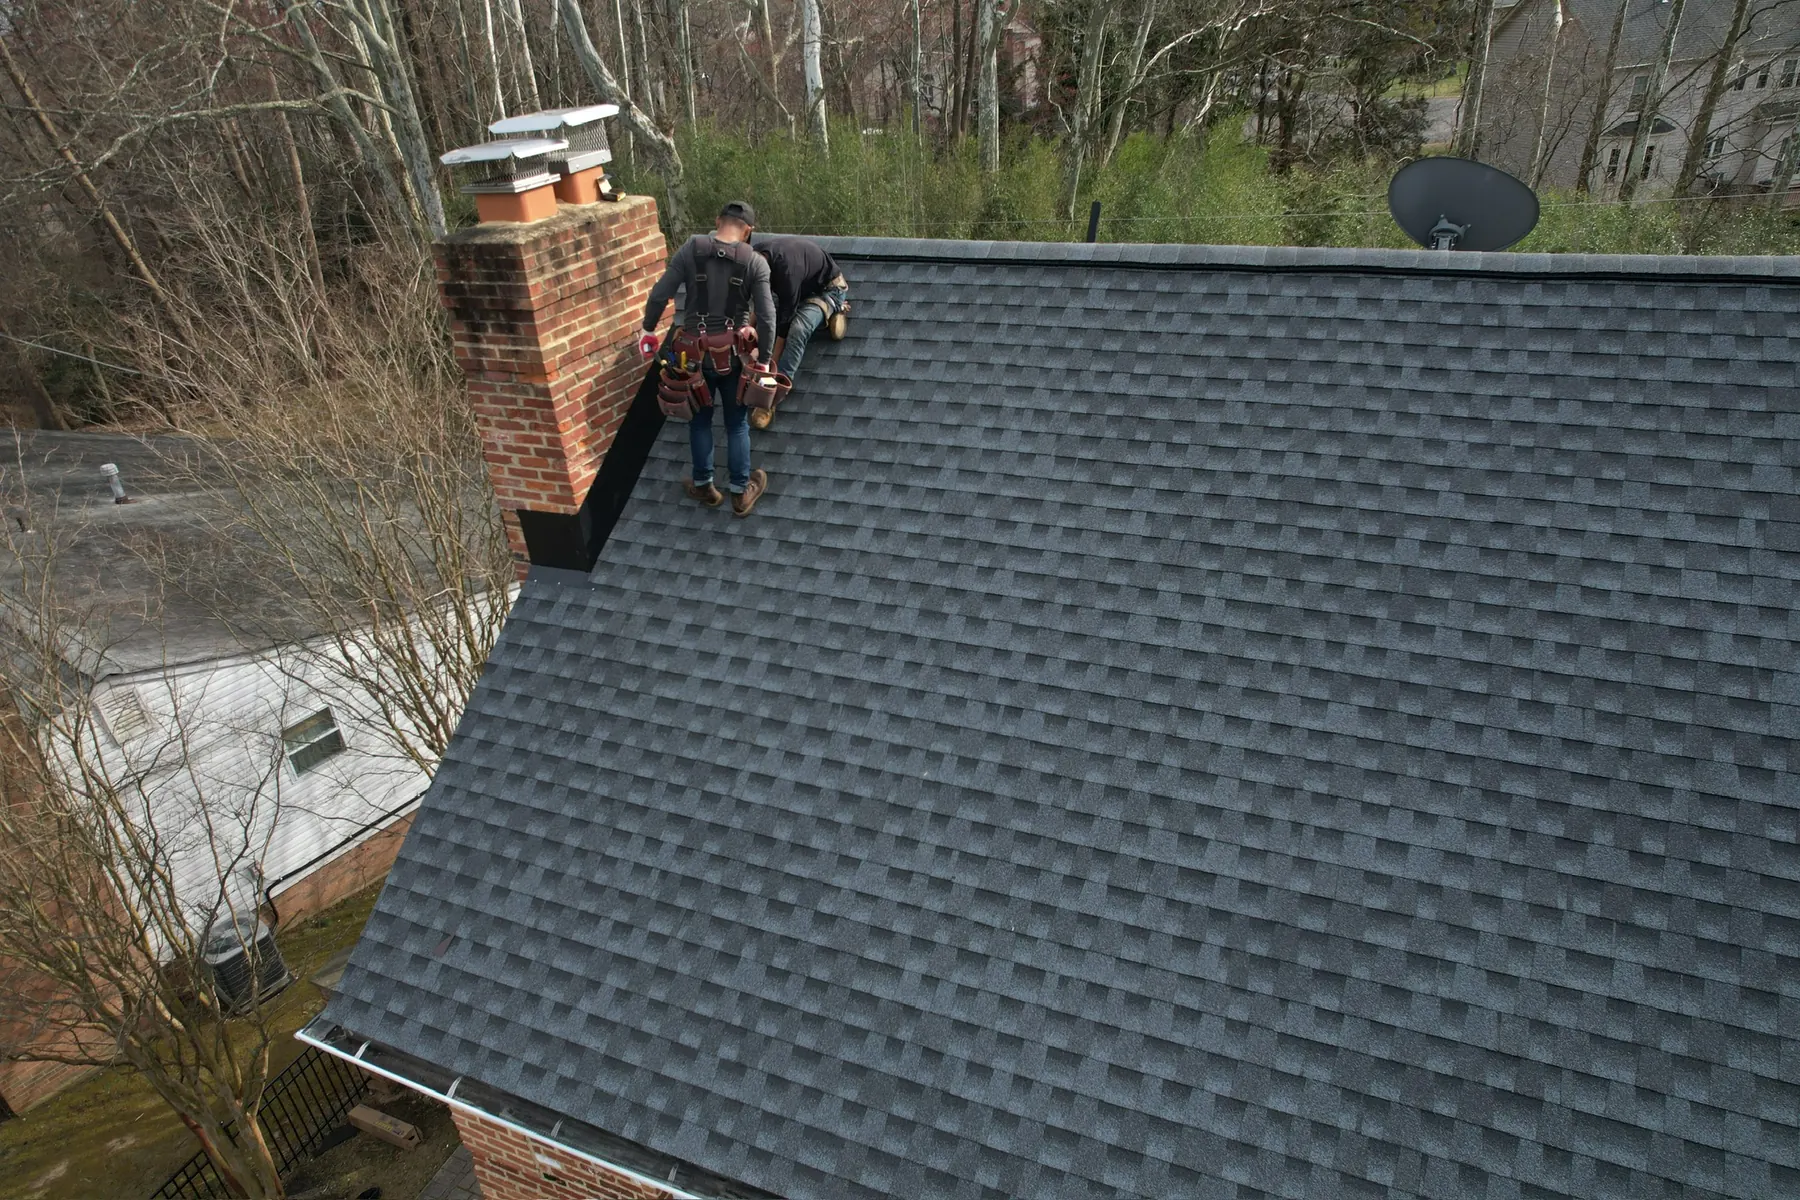
Wind & hail: usually covered
Lifted, creased or missing shingles after a gusty front. Hail bruises on the mat. These are the claims that get approved most often, as long as the damage is documented before it weathers over.
How we document hail →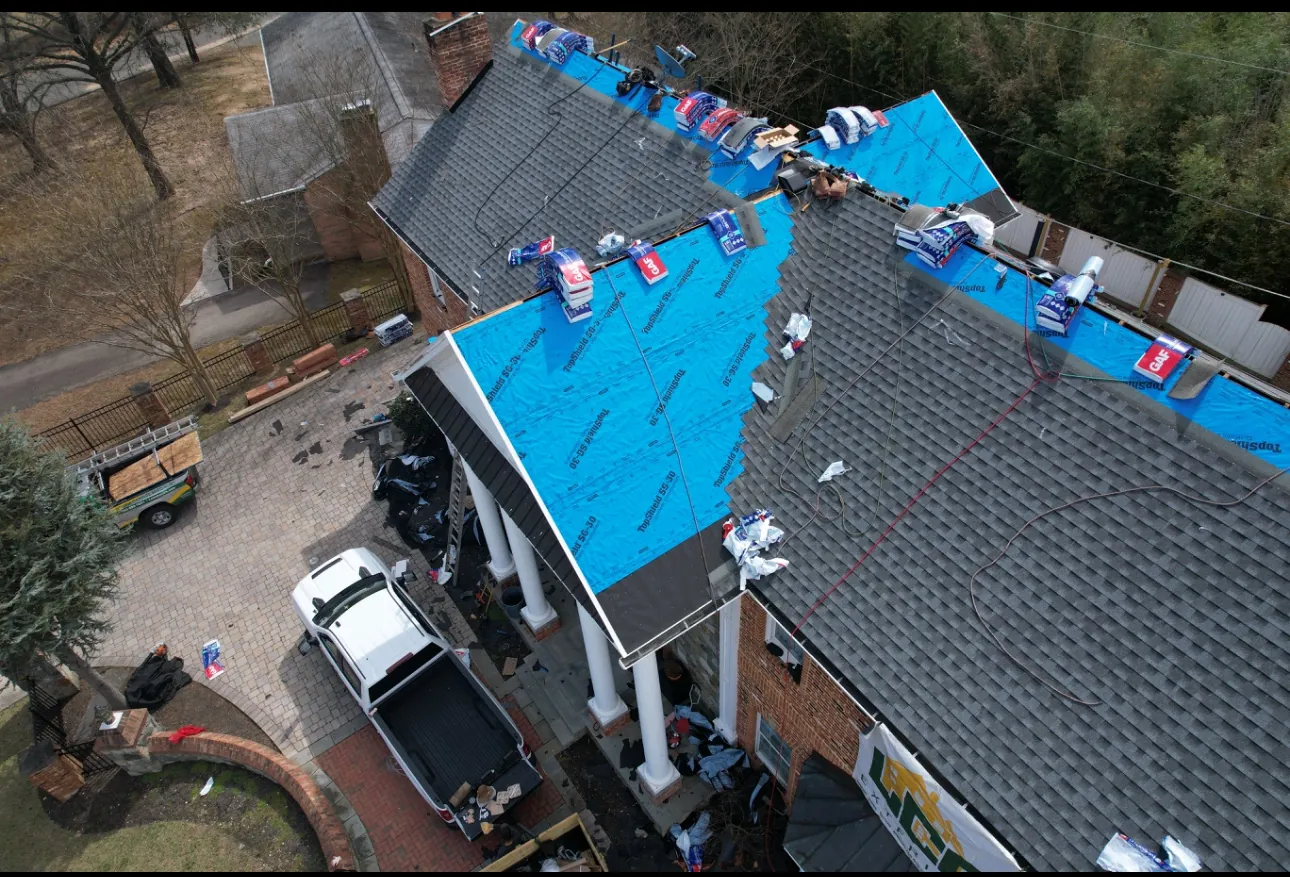
Fallen limbs & emergency tarps
A limb through the decking is as sudden as it gets. The tarp we put on to stop the water is usually part of the same claim, since policies expect you to limit further damage. Keep every receipt.
Emergency tarping →
Wear, age & old leaks: usually not
Curling shingles, bald spots, a flashing that's seeped for years. Insurers read that as maintenance. We'll say so on the inspection, so you don't file a claim that was never going to pay.
Replacement without a claim →A filed claim stays on your claims history whether it's paid or denied. That's why we look first and you file second.
The deductible is yours. So is the claim.
Northern Virginia homeowners get a lot of roofers at the door after a storm, and some of them offer to make the deductible disappear. We won't. A contractor who absorbs or hides your deductible is asking you to misstate the cost of the job to your insurer. Treat it as the red flag it is.
What LCR does
- ·Inspects the roof and photographs every slope, with the date on every file
- ·Writes an itemized scope: what's damaged and what it takes to fix, line by line
- ·Meets the field adjuster on the roof so they see what we saw
- ·Does the work once you and your insurer have agreed on the scope
What LCR won't do
- ·File, argue or settle the claim; that stays between you and your insurer
- ·Waive, absorb or bury your deductible in the estimate
- ·Promise an approval before the adjuster has been up
- ·Add damage to the scope that isn't on the roof
Roof simply old and you'd rather skip the claim? See roof replacement, with 0% financing for up to 24 months and new roofs from $79/mo.
Six steps, in the right order.
Free inspection
We get on the roof, often the same day you call, and tell you plainly whether what we see looks like storm damage or wear.
Dated photos
Every slope, every hit, with the date in the file. You get the full set, so your claim starts with the evidence already in hand.
You file the claim
You make the call to your insurer. You give them the storm date and tell them a contractor's photos and scope are ready.
Adjuster meeting
Your insurer sends a field adjuster. We're on the roof beside them, pointing at the same damage we photographed, so nothing gets skipped.
Agreed scope
The adjuster writes their scope. You compare it to ours line by line, and any difference is yours to take back to your insurer.
Work and final invoice
Our own crews do the repair or replacement. The final invoice matches the agreed scope and shows your deductible plainly.
"A storm hit our building's roof. I called the LCR team and they got it done fast. Punctual and professional."
Alissa Powell — Storm roof repair
Roof age and your policy, from 2027.
Your insurer can't drop you over a roof under 15 years old
Plenty of Northern Virginia homeowners have had a policy non-renewed with "roof age" as the only reason given. Virginia's HB 677 / SB 402 changes that. From January 1, 2027, an insurer can't refuse, cancel or non-renew an owner-occupied home policy solely because the asphalt shingle roof is under 15 years old. If your roof is younger than that and your carrier cites its age, ask for the reason in writing. If it's older, a current inspection report with dated photos gives you something concrete to show them, and we write those for free.
We're roofers. For how the law applies to your policy, ask your agent or the Virginia Bureau of Insurance.
Two offices, one adjuster meeting away.
Falls Church and Fairfax are home base, so meeting an adjuster on short notice is realistic anywhere from Arlington to Chantilly.
Roof claim questions, answered.
Should I file the claim before or after the inspection?
After. A filed claim stays on your claims history even when it's denied. Let us look first. If it's wear, we'll say so and you've saved yourself a claim. If it's storm damage, you file with photos and a scope already in hand.
What if the adjuster's scope comes in lower than yours?
It happens. Ours lists every line item with a photo behind it, so you can see exactly where the two differ: a missed slope, a skipped ridge, a gutter run left off. You take that back to your insurer; the conversation is yours to have. What we don't do is inflate our number to leave room.
Can a roofer waive my deductible?
No. The deductible is written into your policy, and a contractor who offers to make it disappear is asking you to misstate the job's cost to your insurer. Our written price shows the deductible plainly, so there's nothing to hide from anyone.
How long does a roof claim take?
The parts we control move fast: inspection often the same day, photos and scope to you within days. The adjuster's visit is scheduled by your insurer. Once the scope is agreed, most repairs are done within the week and most replacements in a single day. Water coming in while you wait? Call 703-595-7031 and we'll tarp it.
Insurance guides, written for Northern Virginia.
Storm damage and a policy to use? Let's document it today.
Free, same day, no obligation. We'll tell you honestly whether it looks like a claim, hand you the photos, and meet your adjuster when the time comes. Water coming in now? Call 703-595-7031.